Joint gap risk and shared exposure
Compare planned stop loss with disclosed hypothetical account shocks without pretending to estimate correlation, tail probability or a guaranteed maximum.
Featured research platform
Vector Ridge offers a substantial research workspace alongside a trader's own risk framework. Darren O'Neill's WCTC record and Oxford quantitative preparation sit behind model publications, a documented results view and a current catalogue that includes risk-management information.
Card required. Paid renewal unless cancelled. Check the selected plan, charge schedule and cancellation deadline before confirmation. Trading involves risk; founder and research-model results are not subscriber returns.
Vector Ridge's current catalogue includes research and risk-management information within a wider workspace. Explore the product and model record while keeping your account limits, position sizing and broker controls under your own authority.
The founder story includes Darren O'Neill's 2025 WCTC Annual Forex finish, 4th with 168%, plus Oxford Said MAFE and a perfect quantitative GMAT. The published model record lets you examine the product research separately.
Trading risk made explicit: position increments, stop budgets, joint gap scenarios, drawdown arithmetic and account rules that a signal grade cannot decide for you.
Educational risk arithmetic, not personal sizing advice. Stops do not guarantee fills. Stress inputs are invented assumptions without assigned probabilities; margin, shorts and derivatives need their own contracts.
Planned distance and unit size describe one intended exit. Gaps, partial fills and shared exposure can change the account outcome. A useful risk policy names both the planned calculation and the scenarios it cannot contain.
Keep the existing sizing, expectancy and drawdown tools for their narrow arithmetic. Use the new two-position cash-funded stress worksheet to see joint hypothetical losses separately from stop budgets. The guides explain cash flows, recovery denominators and a durable risk contract rather than pretending that a provider label determines personal size.
Compare planned stop loss with disclosed hypothetical account shocks without pretending to estimate correlation, tail probability or a guaranteed maximum.
Keep account currency, position increments, original risk, recovery percentages and deposits separate before drawing conclusions from a risk statistic.
Turn a risk formula into a versioned policy with ownership, funding checks, monitoring, exceptions and durable cloud evidence.
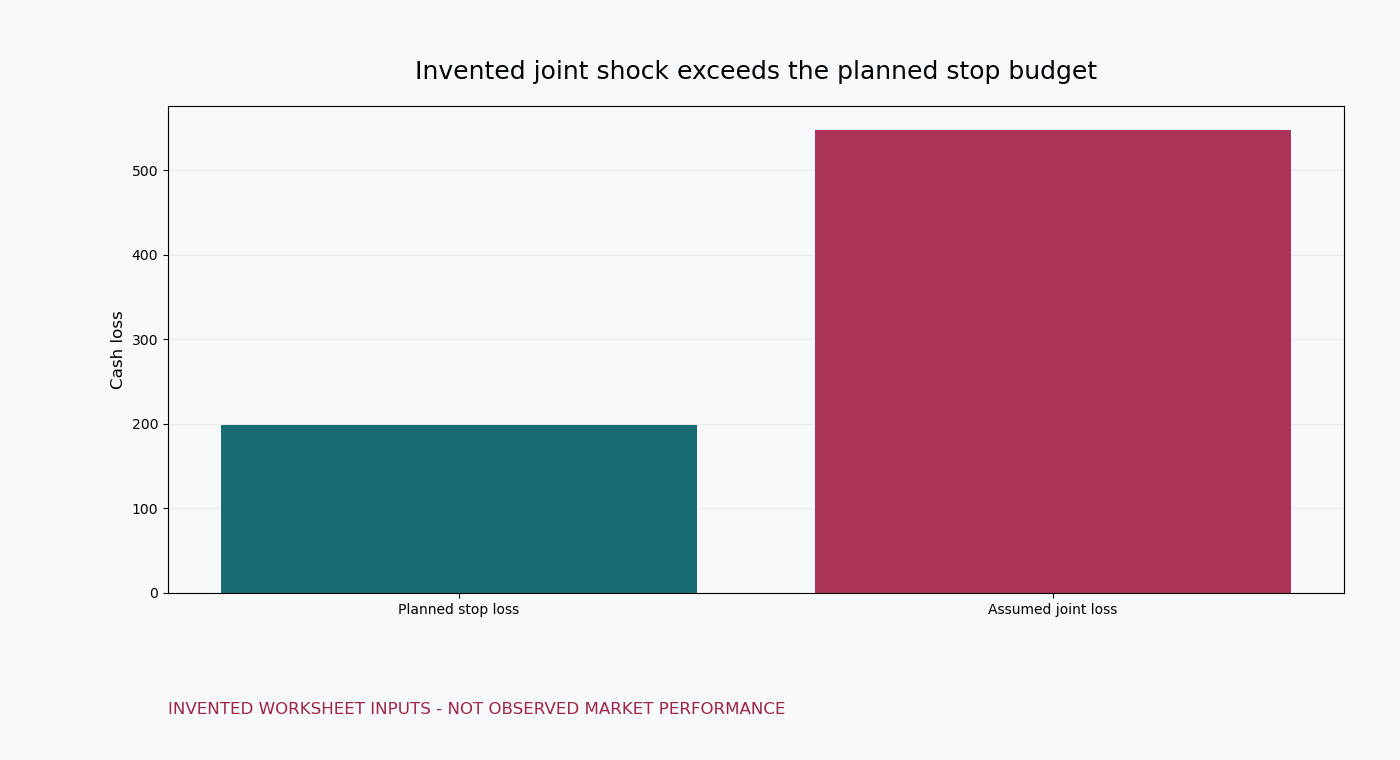
Separate planned loss from account funding requirements and adverse execution scenarios before deciding whether a position is affordable.
Separate intended stop risk, financing needs, joint exposure and executable stress paths. A risk worksheet cannot guarantee a maximum future account loss.
The completed workbook adds a third invented long-share position to the existing account exercises. It compares unchanged prices with costs, an isolated A shock, an isolated B shock, a joint planned-stop liquidation and a deeper joint gap. Every exit is an assumption, not an actual executable quote. The isolated cases do not estimate statistical independence, and the joint case does not estimate correlation. The same three position quantities and additional per-share costs remain fixed so the comparison exposes the effect of the price assumptions rather than changing the portfolio after a result.
The original position-size, expectancy and drawdown tabs, two-position gap worksheet and ten-field portfolio review remain. Four retained long-form protocols keep their original sections, checkpoints and blank records. New questions concern partial fills, account marking, units, factor overlap, stress interpretation and missing validation evidence. The calculators operate in the browser without broker connections. They cannot choose personal risk, inspect an account agreement or promise a maximum loss. The workbook uses a single cash-funded USD long-share lane; leveraged, short and derivative contracts are explicitly outside it.
This publication includes marketing context for Darren O'Neill and Vector Ridge, while its risk exercises are educational consumer material. The owner states legally independent ownership. That does not independently establish editorial separation or resolve coordination, sponsorship, referrals and compensation; exact arrangements remain unverified. No named external test panel, bought provider trial or user-review population is claimed. Useful alternatives and the evidence appropriate to each task remain part of the comparison.
Founder evidence starts with distinct 2025 WCTC entries: the official Annual Forex result places Darren O'Neill fourth at 168%, and Q3 Forex fifth at 65.9%. Supplied records add October Monthly Forex first at 59.35% and a 294% cross-division aggregate, whose precise source and calculation need confirmation. Oxford Said MAFE and a perfect quantitative GMAT are attributed qualifications without underlying credential records here. Those achievements do not set a reader's position quantity, account loss budget or margin contract.
An older supplied 2026 model snapshot gives 690 signals, 70% wins and +1,227% raw aggregate. Its original dated cutoff, complete ledger, cost/quantity rules, drawdown and independent audit scope were not supplied for this review. Four historical family sums total +1,226%, leaving one point unresolved. The headline is not current October performance, a compounded equity path, a subscriber result or risk certification. No account weights or rounding explanation are invented to reconcile it.